
实时更新热门项目资讯,让您紧跟政策不踩坑
 Home
 Property News
Real Estate News
Hong‑Kong Housing Market Booms On Volume‑Price Upturn — Owner‑Occupier Demand Dominates, Local & Mainland‑Chinese Buyers Participate

 2026.11.04
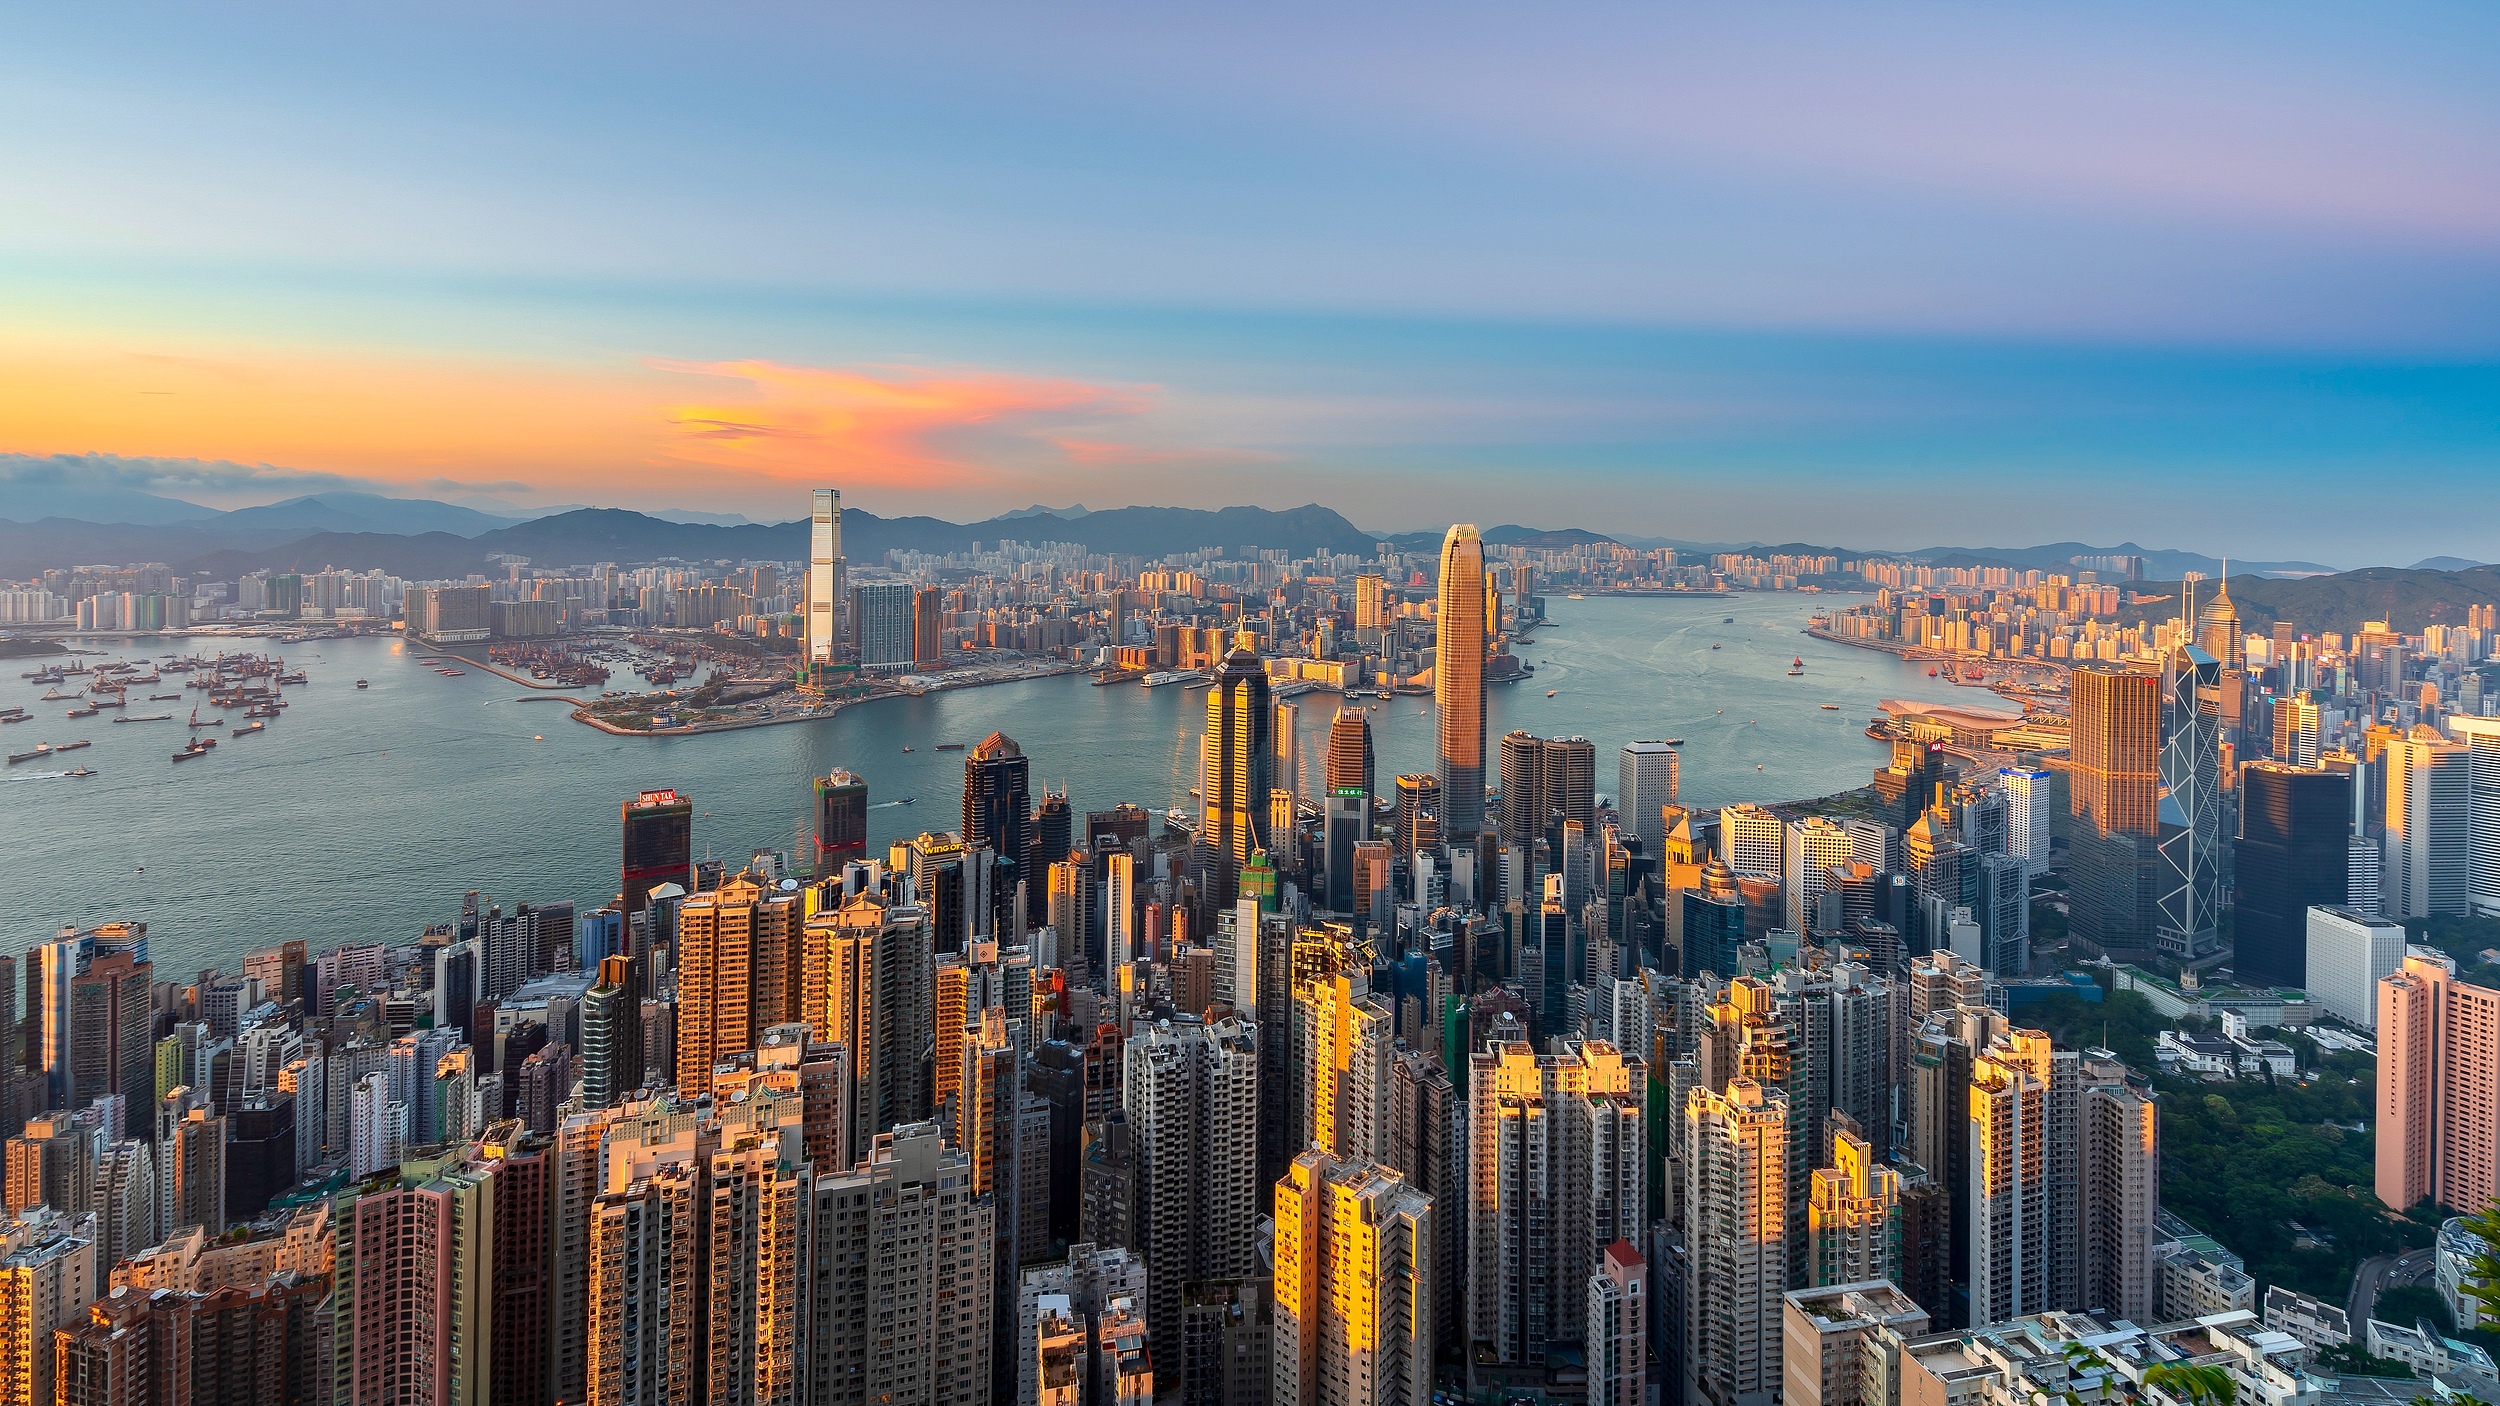
Hong‑Kong residential market recorded simultaneous volume‑price growth in first half of 2026. Rating and Valuation Department data shows private‑residential price index rose for 13 consecutive months. Land Registry figures reveal H1 transaction registrations hit five‑year high since H1‑2021. Unlike previous boom cycles, this recovery is mainly underpinned by genuine owner‑occupier demand. Both mainland‑Chinese buyers and local Hong‑Kong purchasers actively participate in transactions. Rising number of profitable second‑hand resale cases are observed. Nevertheless industry commentators warn that after prolonged price increases, further sharp short‑term upside is limited and the market may enter a consolidation phase.
Core Market Statistics
|
Indicator |
Figure |
Remarks |
|---|---|---|
|
Private domestic price index (Jun‑2026) |
323.2 |
+12.7 % YoY, +0.31 % MoM; 13 consecutive monthly gains |
|
H1‑2026 cumulative index gain |
7.88% |
Compared with Dec‑2025 reading of 299.6 |
|
H1‑2026 total sale registrations |
49,955 cases |
5‑year high since H1‑2021 |
|
H1‑2026 total transaction value |
HK$410.289 billion |
Four‑and‑a‑half‑year peak |
|
Profitable second‑hand private‑home resales (H1) |
13,795 cases |
Five‑year high volume |
|
Profitable resales of post‑duty‑relaxation purchases |
1,601 cases |
Average profit HK$847,000 per completed deal |
Core Market Commentary
Genuine owner‑occupier demand acts as main driver instead of pure speculation
Past Hong‑Kong up‑cycles were often fuelled by heavy short‑term speculative capital. The 2026 recovery is supported largely by local home‑seekers plus new arrivals under talent admission schemes. Investment interest has picked‑up but remains secondary, leading to more stable upward momentum.
Combined purchasing‑power from mainland‑Chinese and local Hong‑Kong buyers
High‑net‑worth individuals and talent migrants from mainland China keep entering the market. Meanwhile local households perceive post‑correction property prices as reasonable, combined with robust rental‑market conditions; many locals purchase for mixed self‑use plus long‑term allocation purposes. Several second‑hand deals show book profits after one‑year‑plus holding period.
Diminishing short‑term momentum; consolidation is likely ahead
After 13 straight months of appreciation, home prices have accumulated substantial gains. Industry consensus points to limited room for further rapid rises; the market is expected to swing sideways rather than keep surging unilaterally.
Talent‑admission policies underpin long‑run housing demand
Ongoing talent‑scheme intakes keep bringing new‑settling households, generating simultaneous buying and rental requirements and providing fundamental support for residential property.
Insights for Mainland‑Chinese Investors In Hong‑Kong Property
Distinguish long‑term allocation from short‑term speculation; do not treat observed short‑term profits as guaranteed returns
Reported one‑year holding profits are case‑specific outcomes under special cyclical conditions, not guaranteed for every asset. Hong‑Kong property is sensitive to interest‑rate and stamp‑duty policy shifts. Short‑term flipping carries material risks; long‑term allocation mindset is preferred.
Expect consolidation after prolonged rally; avoid chasing over‑heated assets
The phase of rapid price appreciation is likely drawing to an end. Do not overpay for hyped properties. Prioritise suburb fundamentals, secondary‑market liquidity and rental yields.
Owner‑occupier‑driven market: liquidity favours mass‑market units
Owner‑occupier buyers dominate current market, so mass‑market medium‑and‑small‑size units enjoy larger pool of prospective successors. Properties in remote suburbs or oversized luxury homes face weaker resale liquidity risk.
Fully model all transaction and recurring holding expenses
Mainland buyers need to budget comprehensively for stamp‑duty, legal fees, rates, management fees and maintenance contributions. Evaluate net returns after all‑in costs instead of only focusing on headline price appreciation.
Talent‑driven benefit is structural but not universal
Demand growth brought by talent schemes concentrates in well‑connected suburbs with solid education and public amenities. Upside will not spread evenly across every district in Hong‑Kong. Suburb‑and‑estate‑level due‑diligence remains essential.
Data sources: Securities Times, Hong‑Kong Rating and Valuation Department, Hong‑Kong Land Registry, Centaline Property public statistics
24小时财富热线
美亚置业集团